
The Morning Call
11/19/26
This is week two of my annual fund raising drive that helps keep me
working for you. Just go to the Donate button and enter the amount. Any monies
will be appreciated.
The
Market
Technical
Wednesday
in the charts.
Wednesday
in the technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
Hedge
funds massively underweight tech.
The squeeze nobody is positioned for.
Thursday morning
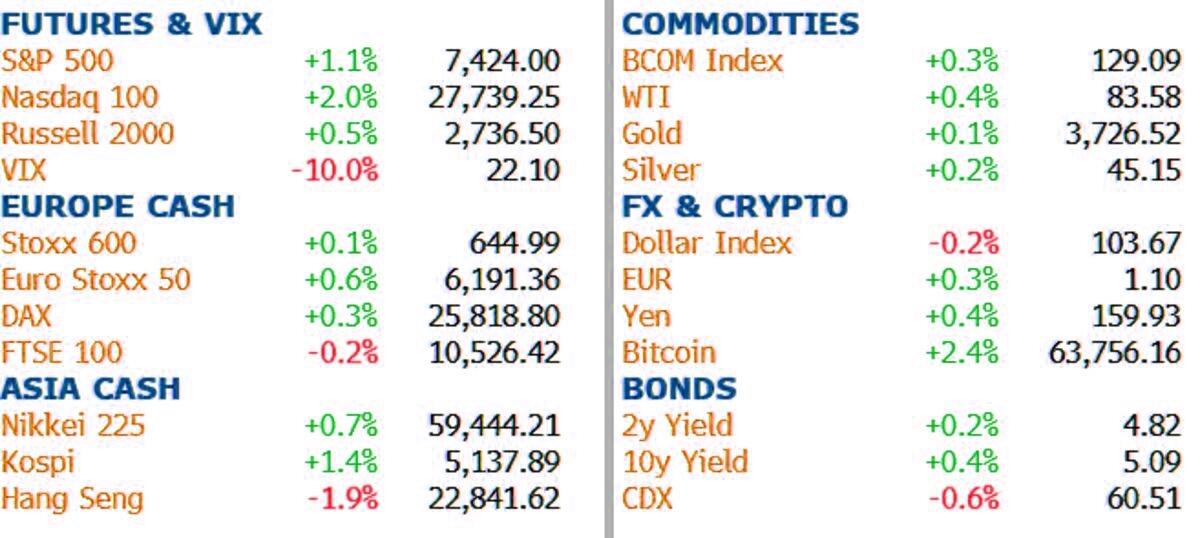
setup: US futures are higher, with Nasdaq contracts ripping as much as 2% after
Anthropic's blockbuster IPO priced well above its marketed range and revived
the battered AI trade, while traders shrug off a fresh round of Iran escalation
(Trump is reportedly weighing new strikes and the IRGC claims two supertankers
hit mines in Hormuz) and parse the first ever Trump-Xi-Putin trilateral in
Shenzhen; as a result the S&P is set to snap a five-day losing streak just
as it was precariously clinging to its 200-day moving average. As
of 8:00am ET, S&P futures are 1.2% higher (trading around 7,424 earlier in
the session) while Nasdaq futures jump 2.0% and Dow futures are +0.6%. The
bounce follows Wednesday's choppy session in which the S&P slipped 0.2% for
a fifth straight decline while the Nasdaq 100 eked out a 0.4% gain, as Nvidia
faded its post-earnings pop to close 3% lower despite a beat and raise.
Premarket, all of the Mag 7 are higher, led by Alphabet (+4.2%) and Amazon
(+2.5%); cybersecurity names are surging after Palo Alto (+9.5%) raised
guidance and agreed to buy Applied Compute for $4.5 billion, dragging
CrowdStrike, Cloudflare and Zscaler higher. The day's driver is Anthropic: the
Claude maker and its seven co-founders raised a record $107.3 billion in an
upsized IPO and private placement, pricing at $83 a share against a $70-$78
range, for a fully diluted valuation of about $1.5 trillion, as we detailed
last night; the stock is indicated 20% to 26% higher in gray market trading
ahead of its Nasdaq debut. Treasuries are slightly weaker, with yields up
1-2bps across the curve and the 10Y at 5.085%, as the risk-on tone unwinds part
of the overnight haven bid; traders still price about 27bps of Fed hikes in
December after hawkish
FOMC minutes showed almost all officials expect more tightening. The dollar
is modestly softer, with the yen lagging (USD/JPY near 159.9) and the Aussie
the worst G-10 performer after a big jobs miss. Oil is steady, with WTI up 0.4%
to $83.59 and Brent at $92.27; gold is nursing losses near $3,730 after briefly
dipping below $3,700, while copper hovers near multi-month lows after
Wednesday's near 6% plunge. Bitcoin trades around $63,700 after its pre-IPO
liquidation slump. US economic data slate includes initial jobless claims and
the November Philadelphia Fed survey (8:30am), the October leading index (10am)
and the Kansas City Fed manufacturing index (11am). Fed speaker slate includes
Hammack (8:50am), Jefferson (9:25am), Goolsbee (12:30pm), Barr (2:15pm), Barkin
(4pm) and Paulson (6:30pm). We also get a $19 billion 10Y TIPS reopening at
1pm.
Fundamental
Headlines
The
Economy
US
The latest Atlanta
Fed Q4 GDP growth nowcast is 3.2% versus a prior reading of 3.4%.
Weekly initial jobless claims totaled 203,000
versus estimates of 197,000.
October pending home sales fell 4.7% versus expectations of -2.0%.
The
November Philadelphia Fed manufacturing index came in at 6.3 versus consensus
of 20.0.
International
September Japanese
machine tool orders were down 0.3% versus predictions of -0.5%.
September EU YoY
construction output declined 1.5% versus forecasts of -2.0%.
The
November UK industrial trends orders index was -12 versus projections of -29.
Other
Update on US business cycle indicators.
Gloomy housing numbers.
https://bonddad.blogspot.com/2026/11/the-autumn-skies-have-turned-gloomy-for.html
Economic growth continues despite Market
turbulence.
https://www.capitalspectator.com/economic-momentum-continues-despite-market-turbulence/
Iran
Overnight news.
Heavily armed
insurgents in Iran’s restive borderlands are posing a new challenge to the
embattled leadership in Tehran, carrying out an increasing number of attacks in
recent months that have targeted regime security forces.
President Trump is
weighing plans for another round of extensive military strikes on Iran, taking
into account new intelligence about Iranian capabilities and intensifying
pressure from Israel to move quickly and aggressively, U.S. and Israeli
officials briefed on the discussions said.
Monetary
Policy
Minutes
from latest FOMC meeting reveal a hawkish Fed.
The case for a 25 (versus 50) basis point rate
hike at the next FOMC meeting.
https://www.aei.org/economics/kevin-warshs-steady-hand-at-the-fed/
It is the money supply, stupid.
https://www.advisorperspectives.com/commentaries/2026/11/18/monetary-muddle
Fiscal
Policy
Too big to bail (out).
Inflation
The
second wave of inflation.
Part two.
AI
Some banks are seeking to reduce AI exposure.
https://giftarticle.ft.com/giftarticle/actions/redeem/bdf0bc3b-990d-438c-9212-21a1e7d4e833
Citadel on the hurdles facing AI.
Investing
Does
the Market have more room to run?
What
would Buffett do?
https://talkmarkets.com/article/what-would-buffett-do
Patience.
https://talkmarkets.com/article/are-we-there-yet-patience-nimbleness
News on Stocks in Our Portfolios
What
I am reading today
Visit Investing
for Survival’s website (http://investingforsurvival.com/home)
to learn more about our Investment Strategy, Prices Disciplines and Subscriber
Service.

No comments:
Post a Comment