
The Morning Call
11/5/26
The
Market
Technical
Wednesday in the
charts.
Note: the good
news is that the S&P (1) bounced off the lower boundary of the trading
range from August, (2) closed above its 100 DMA, reestablishing it as support
and (3) closed that overhead gap down open. The bad news is that it (1) created
a gap up open and (2) challenged its 50 DMA and failed. I know lots of analysts
sound jiggy and believe yesterday’s pin action opens the door for the year end
rally. But failing at the 50 DMA and not yet making a new higher high (within
the current trading range) remains a problem. I need more follow through. If we
get it, I will likely add to my dividend growth ETF trade,
Wednesday in the
technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
The AI trade is
breaking apart.
We have never seen
this before.
https://www.bespokepremium.com/interactive/posts/think-big-blog/youve-never-seen-this-before
Thursday morning
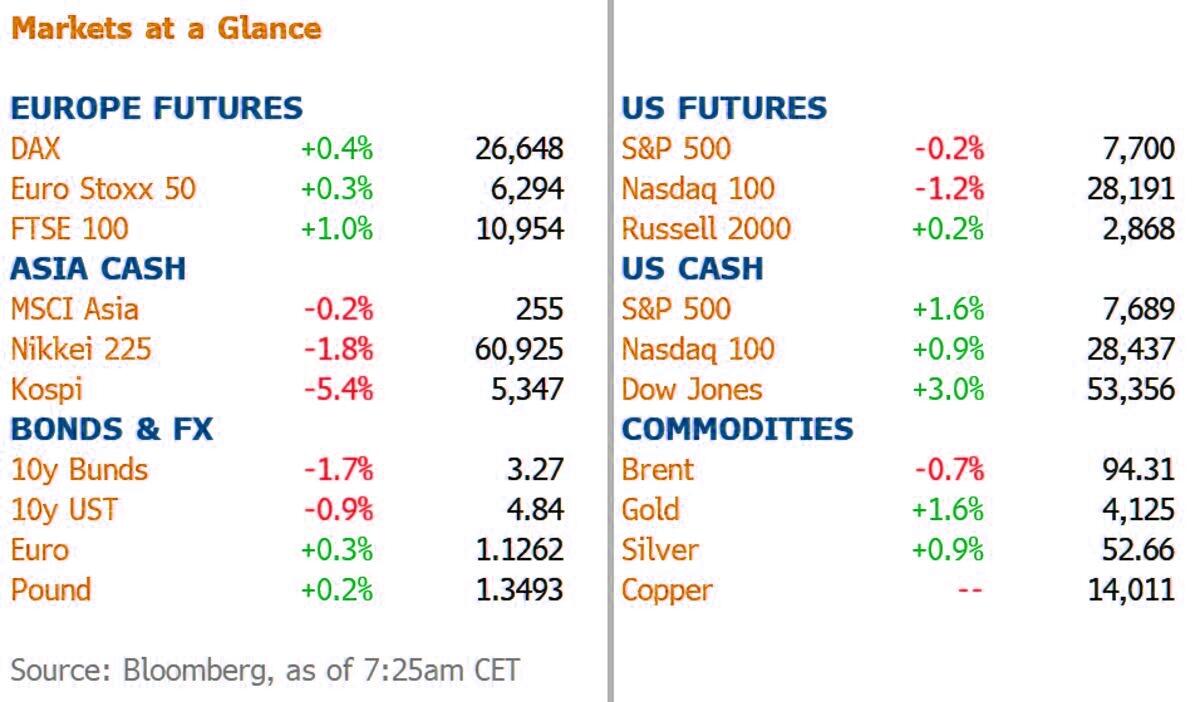
setup: US futures are mixed, with the Nasdaq lagging as the post-midterm
rotation out of chipmakers and the AI complex enters a second day, after the
Democratic sweep raised fears of a data center backlash, Qualcomm tumbled on a
weak forecast and the Kospi crashed almost 6%, while oil rebounded modestly
from Wednesday's plunge and the BoE hiked rates for the first time in three
years; as a result the 10Y yield touched 4.83%, the lowest since Sept. 10. As
of 6:20am ET, S&P futures are 0.1% higher while Nasdaq futures are down
0.5%, Russell 2000 futures add 0.4% and Dow futures are [x%]; this follows
Wednesday's session when the S&P jumped 1.6% for its best day since August
and the Dow soared 3%. In premarket trading, semis are again getting hit (the
SOXX ETF was down 2% premarket per Bloomberg) with Qualcomm sliding 10% after a
lackluster forecast, continuing
the hyperscalers vs semis split we flagged yesterday, while the Mag 7 is
mixed with Amazon and Meta higher and Tesla and Nvidia lower; AppLovin soars
16% on blowout guidance. The day's driver is the blue wave (again): with
Democrats set to control both chambers, traders are pricing tighter regulation
of data centers (Goldman's Alec Phillips sees moratoria potentially hitting about
45% of planned US data centre capacity expansion), a quicker end to the
Iran war and less fiscal largesse, which is why hyperscalers that own compute
are bid and everything that builds, powers or supplies it is offered.
Treasuries are extending their rally, with the 10Y at 4.87% after earlier
touching 4.83%, as the midterm result fuels expectations that the
administration's tax and spending plans will be contained and after the
Treasury's refunding hinted at less long-end issuance. The dollar is flat after
its worst day in two months, cable erased losses after the BoE hiked 25bps to
4% in an 8-1 vote (Mann wanted 50bps) and Bailey warned it was unlikely to be
the last hike unless the Iran war is resolved. In commodities, Brent rebounds
1.6% to $96.15 after crashing almost 9% on Wednesday, as Iran claims tankers
hit mines near Hormuz and Ukraine struck Russia's Ryazan refinery; gold extends
its post-midterm rally above $4,100 and silver trades around $52.7. Bitcoin is
little changed. US economic data slate includes Challenger job cuts (already
out: 43,994 in October, down 71.3% y/y), initial jobless claims, Q3 nonfarm
productivity and unit labor costs (all 8:30am ET). Fed speaker slate includes
Hammack (8:50am), Barkin (9:10am) and Logan (7:00pm). The Treasury sells $115bn
of 4-week and $110bn of 8-week bills at 11:30am.
Fundamental
Headlines
The
Economy
US
Weekly jobless claims totaled 189,000 versus
estimates of 196,000.
Q3
nonfarm productivity rose 3.6% versus projections of +2.8%; unit labor costs
fell 0.7% versus +0.6%.
The September
trade balance was -$105 billion versus consensus of -$108 billion.
The October
services PMI came in at 56.1 versus expectations of 57.9; the October composite
PMI was 55.9 versus 57.6.
October light vehicle
sales totaled 15.5 million units versus forecasts of 15.9 million.
The latest Atlanta
Fed Q4 GDP nowcast was growth of 3.4%.
International
September German
factory orders were up 4.4% versus predictions of 4.8%.
The September EU PPI was up 2.5%, in line.
The October EU
construction PMI was 42.5 versus estimates of 44.0; the October German construction
PMI was 41.6 versus 44.0; the October UK construction PMI was 43.6 versus 46.1.
Other
Interest rates---higher for longer.
The
Election
What changes (and doesn’t)?
What the dem’s win means for the Markets.
https://www.capitalspectator.com/what-democrats-midterm-win-means-for-markets/
AI
What is next for data centers?
Tariffs
Undoing Trump’s
tariff fiasco.
Tech
accounts for 2/3rds of the US trade deficit.
https://talkmarkets.com/article/tech-now-accounts-for-two-thirds-of-the-us-trade-deficit
Investing
Reviewing Q3 earnings.
https://www.carsongroup.com/insights/blog/earnings-check-in-following-the-money/
How to turn your
cash into wealth.
Record fixed
income inflows.
What credit spreads are telling us.
https://talkmarkets.com/article/credit-spreads-calm-on-the-surface-concern-at-the-bottom
The value of having
a ‘stop loss’ discipline. The theme of the article is right on. However, in
deciding on whether to have an actual stop loss versus a mental one consider
this. The market maker sees your order as well as everyone else’s. If a stock
is declining and the market maker sees a number of stop loss orders and feels
like those orders are near a trading low, he can manipulate the ‘at the market’
sell orders down to a level that triggers your stop loss. Then he buys the
stock for his own book and sells it at a higher price. So, my recommendation is
to have a mental stop and the balls to stick with it.
https://talkmarkets.com/article/are-you-your-own-worst-enemy
News on Stocks in Our Portfolios
What
I am reading today
Visit Investing
for Survival’s website (http://investingforsurvival.com/home)
to learn more about our Investment Strategy, Prices Disciplines and Subscriber
Service.

No comments:
Post a Comment