
The Morning Call
11/6/26
The
Market
Technical
Thursday in the
charts.
Thursday in the
technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
Note: the good
news (that’s a joke) is that the S&P closed Wednesday’s gap up open. The
bad news is that the fecal matter hit the rotating blades. The index blasted decisively
back through its 100 DMA and the lower boundary of the trading range dating back
to August and is poised to challenge its 200 DMA (~7318). Were that challenge
to be successful, the next visible support level is the lower boundary of its
short term trading range (~6642). So the bottom line for the day is---let’s
hope the 200 DMA holds.
The NASDAQ is
crashing.
$47 billion in
levered ETF selling.
The latest from Goldman’s desk.
Friday morning
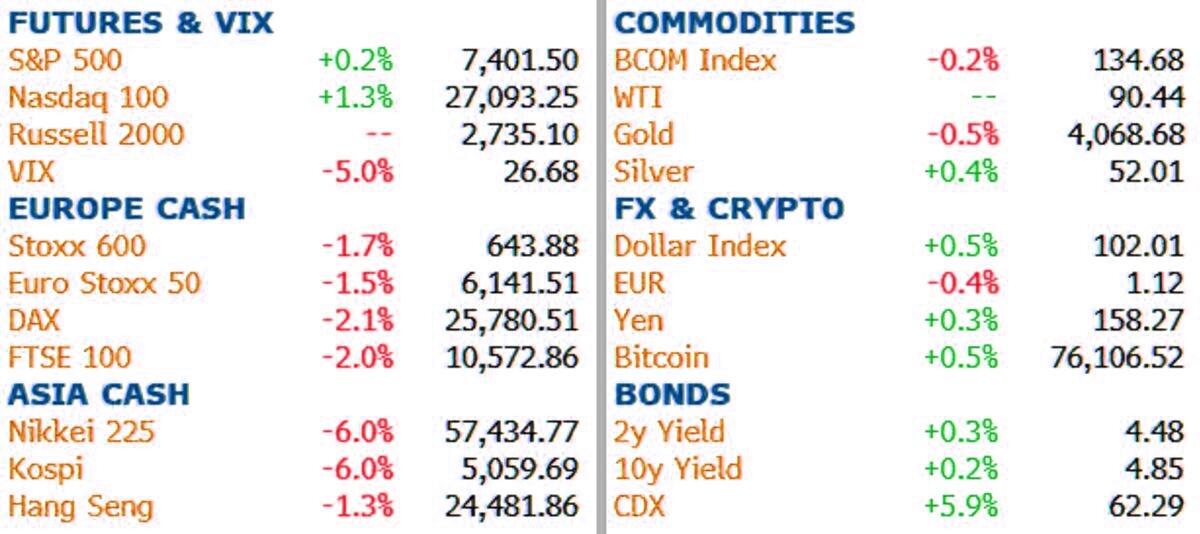
setup: US futures are higher, led by a sharp rebound in semis and memory names,
as dip buyers emerge after Thursday's AI bloodbath which saw the Nasdaq 100
suffer its worst day since March 2020, while traders brace for the October jobs
report; at the same time the dollar is up against every G10 currency and oil
reversed an early jump above $100 after Qatar's Emir and Trump discussed
de-escalating the Iran war, leaving the 10Y yield fractionally higher at 4.86%
as the "sell everything" day gives way to a "buy what got
hit hardest" morning. As of 8:05am ET, S&P futures are 0.1%
higher at 7,390 while Nasdaq futures are up 1.3% at 27,100 and Dow futures are
down 1.1%, as the rotation out of tech and into everything else reverses. On
Thursday, the S&P 500 tumbled 4.4%, its worst day since April 2025, the
Nasdaq 100 plunged 6.4% and the Philly semis index crashed 12%, wiping out
$2.3 trillion in tech market value (and tech
hedge funds' entire 2026 gain), as the Democratic midterm sweep stoked
fears of a regulatory crackdown on the AI buildout. In premarket trading, chip
and memory stocks are retracing roughly 30-40% of yesterday's losses according
to JPM: Micron +7.8%, AMD +7.1%, Intel +4.7%, Broadcom +4.4% and Nvidia +4.3%,
while Lam Research jumps 10% after unveiling a $25 billion buyback; outside of
AI, Cloudflare and Airbnb soar on strong guidance while DraftKings and
Atlassian tumble. The day's driver is AI (again): having been the
market's biggest tailwind for three years, the AI capex trade is now its
fulcrum, and the only question that matters this morning is whether Thursday's
six-standard-deviation puke in semis was capitulation or, as we
asked last night, just the opening act. Treasuries are slightly weaker
after a two-day haven rally, with yields 2-3bps cheaper across the curve and
the 10Y around 4.86%, near the session high, while swaps now price about 72%
odds of a December Fed hike, down from near 80% on Tuesday. The Bloomberg
Dollar Spot Index is up 0.2% at a one-week high, with the Aussie sliding to a
seven-month low and cable suffering its biggest drop since mid-October. In
commodities, Brent briefly topped $100 as Iran claimed two tankers hit mines in
the Strait of Hormuz, before sliding to as low as $98 after the Qatar call, WTI
is up 0.5% at $90.94, and gold drops 0.5% to about $4,069/oz. Bitcoin trades
just above $76,000. US economic data slate includes the October jobs report
(8:30am), the November preliminary University of Michigan sentiment (10am) and
September consumer credit (3pm). Fed speaker slate includes Musalem (9:10am),
Bowman (12:15pm) and Daly (1pm).
https://cms.zerohedge.com/sites/default/files/inline-images/image_0.jpeg
Fundamental
Headlines
The
Economy
US
October
nonfarm payrolls rose by 165,000 versus estimates of 65,000; the unemployment
rate was 4.1% versus 4.2%; average hourly earnings were up 0.4% versus +0.3%.
International
September
Japanese YoY average earnings were up 4.6% versus expectations of up 3.8%.
September
German industrial production was up 0.7% versus consensus of 0.0%.
September
EU retail sales fell 0.7% versus projections of down 0.1%.
Other
What happens to the dollar as
US equities go down?
https://mrzepczynski.blogspot.com/2026/11/the-profit-dollar-period-is-here.html
Three signs of a cash strapped consumer.
Update on new home affordability.
https://politicalcalculations.blogspot.com/2026/11/new-homes-hovering-just-below-upper.html
Is 7% the no-go zone for home mortgages?
Analysis of the November ISM numbers.
https://bonddad.blogspot.com/2026/11/the-economically-weighted-ism-averages.html
Iran
Overnight news,
https://www.zerohedge.com/geopolitical/trump-says-us-locked-and-loaded-renewed-strikes-against-iran
Monetary
Policy
The Bank of England raises rates.
Midterm election results takes pressure off
the Fed.
AI
The
AI junk bond blast radius.
Investing
The yield curve has a nasty surprise for the
AI trade.
Real estate in a
5% world.
What the midterm elections mean for your
money.
Q3 earnings
scorecard.
https://talkmarkets.com/article/q3-earnings-scorecard-solid-beats-upward-revisions-and-ai-drivers
Central bank gold
purchases were highest of the year.
News on Stocks in Our Portfolios
What
I am reading today
Surrendering the ability to think.
https://www.safalniveshak.com/deskilling-the-investors-mind/
Visit Investing
for Survival’s website (http://investingforsurvival.com/home)
to learn more about our Investment Strategy, Prices Disciplines and Subscriber
Service.

No comments:
Post a Comment