The Morning Call
11/16/26
This is week two of my annual fund raising drive that helps keep me
working for you. Just go to the Donate button and enter the amount. Any monies
will be appreciated.
The
Market
Technical
The S&P took us
on a wild ride last week. But in the end, it ended up pretty much where it
started---stuck between its 100 and 200 DMAs and below a developing downtrend
off its October 6 high. On the plus side, it (1) remains above its 200 DMA, (2)
it is in uptrends across all major timeframes, (3) we are in a very positive
seasonal period and (4) third quarter earnings were gangbusters and likely to repeat
themselves in the fourth quarter. On the minus side, (1) inflation remains a
problem and we have an FOMC meeting in our near future, (2) the uncertainty around
the AI buildout just got a little more so thanks to Jensen’s inability to keep
his dick in his pants, (3) the Iran war remains a murky as ever and (4) we have
a new congress whose new entrants hold some notable anti-Market sentiments. So,
the question remain is the worsts over? And I, again, have no clue. I remain on
sidelines until the Market shows me.

The bond market got
hammered last week, Obviously, the bond boys were a lot more concerned with the
negatives noted above than the stock guys. TLT is back below all DMAs and
continues in downtrends across all timeframes
I sold my small trading position in a TIPS ETF.

GLD investors weren’t
any more pleased with last week’s news/economic stats than the bond boys. It
retreated back below the lower boundary of its short term trading range. And is
below all three DMAs. Nothing to do here.

The dollar clearly liked higher rates It remains on
a pretty steep upward trajectory and above all three DMAs. And while it has
made a nice series of higher lows and higher highs and seems likely to continue
to do so, it remains in about the middle of a wide short term trading range.

Friday in the charts.
https://www.zerohedge.com/markets/everything-bad-everywhere-all-once-except-stocks-jensen-quits-inflation-hits-market-splits?gift=eyJhbGciOiJIUzI1NiIsInR5cCI6IkpXVCJ9.eyJuaWQiOiIxMTMyMjE2Iiwic2VuZGVyVWlkIjoiUUhnc3BaZVVFS2E3RHhXM216eFlKbjhaWEFoMiIsImlhdCI6MTc5NDY3NDQ3NywiZXhwIjoxNzk3MjY2NDc3LCJhdWQiOiJ6aC1naWZ0In0.7E7Aqe3hMGxfBOaSGidRJYEXsfOkYil1lCICEiDHp-0
Friday in the technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
Monday morning
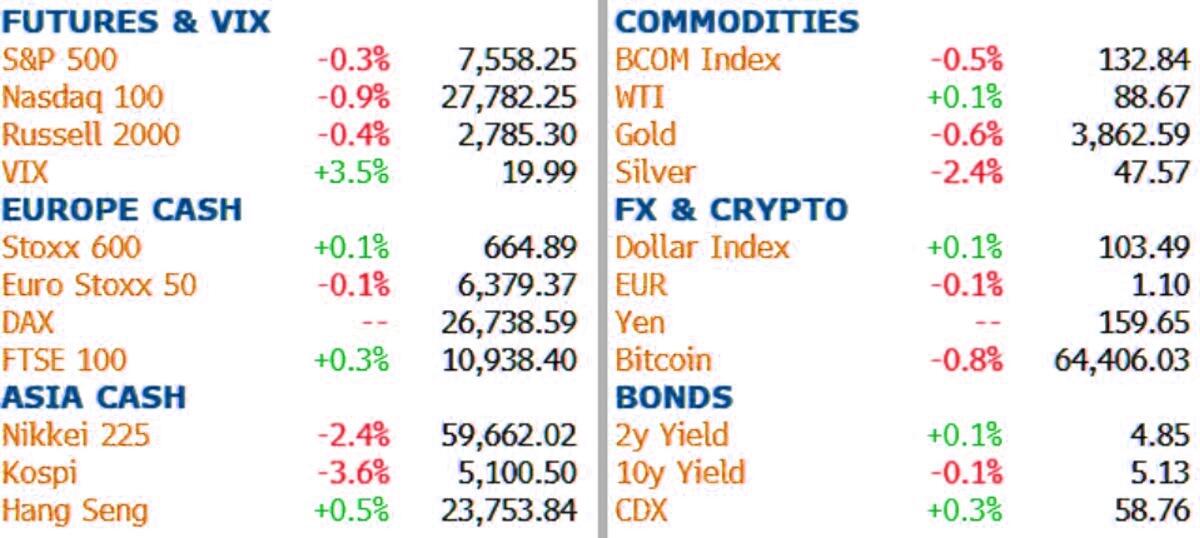
setup: US futures are lower as the AI selloff resumes on a Monday packed with
risk: Asian chipmakers were obliterated (Taiwan's Taiex plunged 6%, the Kospi
lost 4%) as the Nvidia leadership soap opera took another turn, with the FT
reporting that ousted CEO Jensen Huang is discussing a comeback just as
Treasury Secretary Bessent demanded a dramatic shakeup and an outside CEO, all
ahead of Nvidia's first post-Huang earnings on Tuesday, the Anthropic IPO later
this week and Fed Chair Warsh at noon today; meanwhile Iran struck a Bahrain
air base for the second time in three days and more tankers hit mines around
Hormuz, yet oil is flat and 10Y yields are pinned at 5.13% after last week's
biggest weekly jump since April 2025. As of 8:15am ET, S&P futures are down
0.5% around 7,542 while Nasdaq futures slide 1.3% and Dow futures are barely in
the red. On Friday, the S&P fell 0.4% and the Nasdaq 0.9% as Nvidia capped
its worst week since April 2025, although the S&P still ended the week
higher and snapped a four-week losing streak. In premarket trading, the Mag 7
is mixed with Microsoft (+0.8%) and Apple (+0.6%) higher while Nvidia (-2.3%)
drags; semis are hit again (Broadcom -3%, Intel -4.5%, Micron -4.8% after a
fatal accident halted part of its Taichung fab), with AI infra and crypto
proxies hammered (CoreWeave -5.9%, Coinbase -6.6%, Strategy -7.4%), while
Take-Two jumps 3.2% on strong GTA VI pre-orders; the selling in Korean memory
names comes as reports of a memory-collusion lawsuit hit the tape, confirming
our article from Friday that a
judge refused to toss the DRAM cartel suit against Samsung, SK Hynix and Micron.
The day's driver is, once again, Nvidia: the stock is down 34.6% over
six weeks per JPM, the board is under pressure from Washington and from Huang's
Silicon Valley allies, and options imply a roughly 7.8% move on earnings, the
biggest implied swing in two years. In rates, Treasuries are steady after last
week's rout (2Y +33bps, 10Y +28bps on the week) as traders await Williams and
Warsh, while gilts lead a selloff in European bonds, pushing the UK 2Y yield to
5% for the first time since 2023 after BOE chief economist Pill said the MPC
has further to go on hikes. The Bloomberg dollar index rises for a fifth day to
its highest since May 2025, EUR/USD is flirting with 1.10 and the Aussie is the
G10 laggard after weak China data. In commodities, WTI slips 0.4% to $88.21 and
Brent is at $95.15 as a well-supplied physical market and Goldman's warning of
a sizable surplus next year offset the Gulf attacks; gold drops 0.6% to $3,862
and silver slides 2.4% to a fresh cycle low near $47.6, while copper hits a
four-month low. Bitcoin trades around $64,400 after tumbling to $62,000 on
Sunday. US economic data slate includes November Empire Manufacturing (8:30am);
Fed speaker slate includes Williams (9:05am), Warsh (12pm) and Hammack
(2:15pm), with Barr having spoken at 5am. Treasury sells $95BN of 13-week and
$82BN of 26-week bills at 11:30am. Mexico's markets are closed for a holiday.
Fundamental
Headlines
The
Economy
The
stats last week were downbeat, with one negative primary indicator and one plus
and one minus inflation numbers. Overseas, the data was negative for a second
week with two neutral price measures.
While
these reports generally support both my forecasts for growth (muddle through) and
inflation (good as it is going to get but not any worse), the level of
uncertainty remains elevated.
First,
Tuesday’s CPI reading is causing a lot heartburn in both the equity and bond
markets---as it should. Between a cowardly Fed and a spendthrift government,
the odds of higher interest rates grew. And that generally makes for downward
revisions in economic (earnings) growth as well as fears of still higher
inflation.
Further,
Trump’s Iran policy seems to have shifted away from kinetic warfare. Investors
first take was some settlement was possible and with it increased oil supplies
and lower prices. That appears to be giving away to the realization that (1) the
real bottleneck is now refining capacity [given the destruction of
infrastructure] and (2) that Trump’s strategy appears to have changed to one of
‘starving them out’ meaning limited Iranian oil gets to market and the chances
of a military flare up are not as low as was initially assumed [i.e., the more desperate
the leadership becomes, the higher the probably of some desperate reaction.]
The
other source of uncertainty came from AI developments. The headline, of course,
was the Jensen Huang/Nvidia scandal. The principal issues being (1) would the
company be able to replace him with an equally gifted leader and (2) the amount
of time and effort on the part of the new leadership that will be consumed
having to addressing [a] the violation of US law regarding the transfer of
semiconductor technology to the Chinese and [b] management/the Board’s
responsibility for oversight and accountability. I am not saying something
terrible will occur; I am saying no one knows---which creates a level of
uncertainty that will likely impact valuations, at least in the short term.
In
addition, the debate around the financing of the AI buildout continues.
Specifically, given the new dem control of many states’ government apparatus
and their desire to slow the buildout, how many projects will be allowed to go
forward, at what speed, at what cost, who benefits, who doesn’t and by how
much? Everyone is trying to figure that out right now---and, as yet, we don’t
have an answer. But most agree that whatever the outcome, while it will be less
positive than previously thought, the growth rate of the AI buildout will
remain above average.
So,
there is both good news and bad news. The bad news is that the projected growth
rate of the AI buildout (and hence the economy) will be less than expected. How
much less. Too soon to determine. But clearly that will overhang the economic
projections as well as the Market until the answer become clearer.
***(I
linked to Goldman’s initial economic forecast for 2027 in last Friday’s Morning
Call; and it was very upbeat. But I am hesitant to put my money on a single
forecast this early and without knowing how aggressive dems will be in
delaying/halting the AI buildout)
And
this from my favorite pessimist.
And
this from Howard Marks.
The
good news is that less demand coupled political deadlock (i.e., hopefully a
less irresponsible fiscal policy) would reduce inflationary pressures. Add in
the democrats’ other objectives to (1) reduce tariff s and (2) wind down the
Middle East war and we could see meaningful progress against
inflation---assuming the Fed doesn’t f**k it up. Again, how this all works out
is currently unclear. So we can’t get too jiggy until more on known.
The
bottom line here is that economic projections from any quarter have become more
iffy. There is both good and bad potential news that will play on growth and
inflation. Until we have a better handle on the outcome of the various
aforementioned developments, a level of uncertainty will prevail which clearly
includes my own forecasts.
US
The
November NY Fed manufacturing index came in at 7.8 versus forecasts of 18.0.
International
September Japanese
industrial production was up 0.2% versus predictions of +0.3%; Q3 preliminary
GDP was flat versus +0.1%; Q3 preliminary capital expenditures were up 1.6%
versus +1.5%; Q3 preliminary private consumption was down 0.3% versus -0.2%.
October Chinese
YoY industrial production rose 4.8% versus consensus of +5.3%; October YoY retail sales were up 0.4% versus +0.8%;
the October unemployment rate was 5.1% versus 5.2%.
Other
The state of the housing market.
Analysis of Friday’s PPI number.
https://bonddad.blogspot.com/2026/11/october-producer-prices-confirm.html
Recession indicators turn green; labor quality
hasn’t.
https://talkmarkets.com/article/recession-indicators-turned-green-job-quality-hasnt
AI
Blackstone couldn’t sell $800 million data
center debt.
Investing
The
latest from BofA.
News on Stocks in Our Portfolios
What
I am reading today
Visit Investing for Survival’s website (http://investingforsurvival.com/home) to learn more about our Investment Strategy, Prices Disciplines and
Subscriber Service.