
The Morning Call
11/2/26
The
Market
Technical
The S&P really
took it on the snoot on Friday, closing below its 50 DMA (if it remains there
through the close on Monday, it will revert to resistance), its the 100 DMA (if
it remains there through the close on Tuesday, it will revert to resistance)
and is sitting on the lower boundary of a trading range dating back to early
August. The $64,000 question is, was this just another one of the sporadic one
day plunges that it has experienced over that time frame or is this the
beginning of a new down move? Technically speaking, it is too soon to assume
that a downtrend is in the making. Plus, Friday’s huge gap down open suggests
the potential for some recovery. Further, the plunge is largely confined to the
tech sector (our Portfolios were only down fractionally on the day), so this
could be following a number of patterns that I suggested earlier---(1) high
flying tech sells off while the rest of the Market holds firm or even advances,
(2) the two Market sectors continue to oscillate or (3) both decline (rise) the
bulk of which is in tech (the rest of the Market).
Of course, fundamentally,
I can name a number of reasons to assume the worst: (1) turmoil in AI, (2)
fears of renewed fighting in the Middle East, (3) a cowardly Fed, (4) an out of
control fiscal policy and (5) the elections.
Bottom line: while
the aforementioned combination of conflicting factors increases my level of
uncertainty, I think it too soon to get beared up. But clearly, Friday could be
a warning shot. Follow through and prudence.
The setup for a
bounce.

The bond market was
basically flat on the week. While TLT was up on Friday, its pin action
certainly did not suggest a flight to safety. In addition, TLT continues to
trade down across all timeframes and is below its 100 and 200 DMAs. As you
know, I bought a small position in a TIPS ETF two weeks ago. But I am waiting
for more information from both the stock and bond markets before increasing
that holding.

Somewhat
surprisingly, GLD followed stocks down in spite of the fairly neutral
performance from bonds and the dollar---which historically it is more (inversely)
correlated to than stocks. However, like the S&P it made a gap down open
and pushed through a critical technical support level (the lower boundary of
its short term trading range; if it remains there though the close on Monday,
it will reset to a downtrend). And it remains below all three DMAs. It seems to
be telling us that higher yields and a strong dollar are in the offing, though
neither is acting that way. Color me confused and on the sideline.

The dollar roller coastered the week, first
advancing then closing basically unchanged. Nonetheless, it remains on a pretty
steep upward trajectory and above all three DMAs. And while it has made a nice
series of higher lows and higher highs and seems likely to continue to do so,
it remains in about the middle of a wide short term trading range.

Friday in the charts.
https://www.zerohedge.com/markets/lula-shock-ai-block-new-smoking-barrels-october-spooks-bond-vigilantes-midterms?gift=eyJhbGciOiJIUzI1NiIsInR5cCI6IkpXVCJ9.eyJuaWQiOiIxMTMwMzc5Iiwic2VuZGVyVWlkIjoiUUhnc3BaZVVFS2E3RHhXM216eFlKbjhaWEFoMiIsImlhdCI6MTc5MzM5ODY0NywiZXhwIjoxNzk1OTkwNjQ3LCJhdWQiOiJ6aC1naWZ0In0.AwBtZMMp2_c4AKV9uCPh106BodcYvxxKOdP6T1a8ehU
Friday in the technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
Monday morning
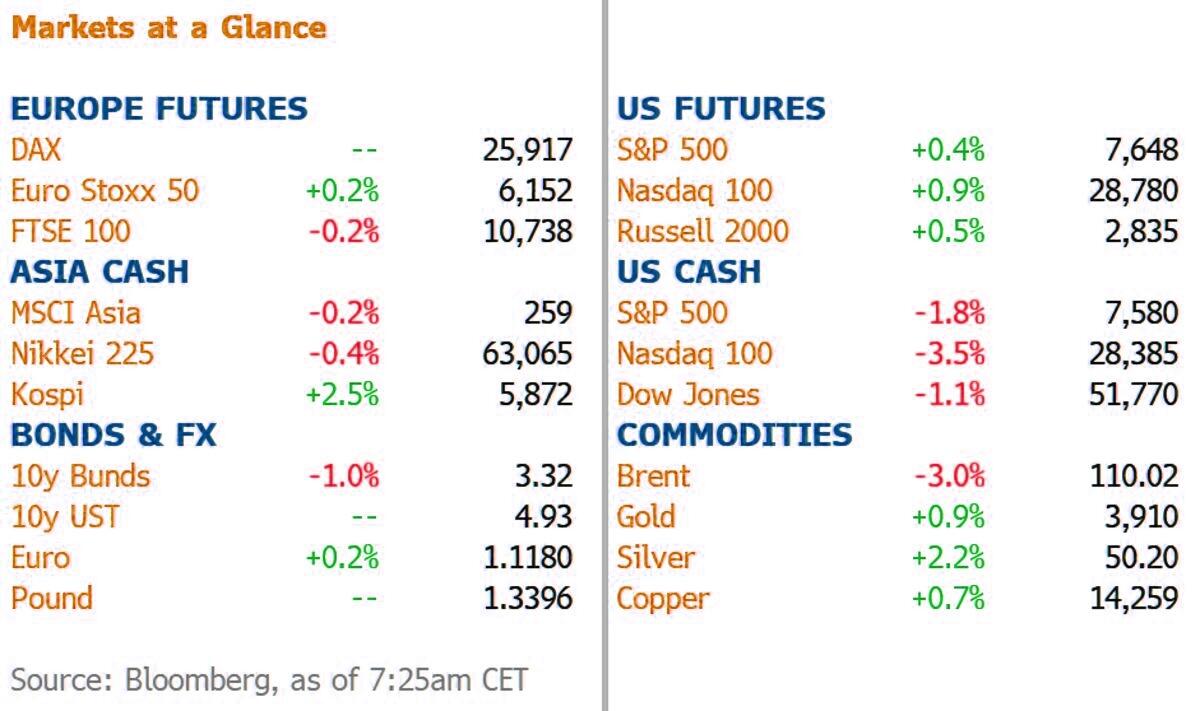
setup: US futures are higher as a slide in oil, a tentative tech rebound and
some old-fashioned seasonality lift sentiment on the eve of the midterms: crude
tumbled more than 4% after Axios reported that Trump told Netanyahu he wants to
give diplomacy with Iran more time before resuming strikes, chips bounced after
Friday's 7.2% SOX puke, and Chinese stocks jumped as Beijing convened yet
another market rescue meeting; as a result Nasdaq futures are up almost 1% and
WTI is back below $100. As of 8:00am ET, S&P futures are 0.3% higher at
7,638, well off session highs, while Nasdaq futures rise 0.6% to 28,758 and Dow
futures are 0.4% higher. On Friday, the S&P fell 1.8% and the Nasdaq 100
tumbled 3.5%, the worst day for both since June, capping a month in which the
Nasdaq 100 lost 6.7% while the equal-weight S&P gained 5%. In premarket
trading, Mag 7 names are mostly higher led by Nvidia and Alphabet, which opened
the books on a seven-part bond offering spanning two to 19 years; Apple dips
ahead of its earnings after the close. Semis and memory names rebound, while
energy names slide with crude. The day's driver is oil (again): Brent
dropped as much as 4.4% to around $108.40 and WTI to $99.59 after the Axios
report, and despite Goldman raising its year-end Brent forecast to $105 from
$90; Iran's FM said Qatar-mediated talks are making progress while Supreme
Leader Mojtaba Khamenei ordered commanders to prepare for renewed
confrontation, so the post-midterm strike window remains very much open.
Treasuries are mixed with the curve pivoting flatter: long-end yields are about
2bp lower on the oil slump while the 10Y is little changed near 4.92%; gilts
outperform, with the 10Y yield down about 5bp to 5.23%, the lowest since Sept.
23, on lower oil and gas prices, while OATs edge higher despite Fitch cutting
France's outlook to negative in an unscheduled move. The Bloomberg Dollar Spot
Index drops 0.2% to a one-week low and the euro jumps 0.5% to 1.1214, its
biggest gain in more than two weeks. In commodities, gold rises about 0.6%
toward $3,900 and silver climbs back above $50, while LME copper gains 0.8%.
Bitcoin trades just below $78,000 as Binance customers pull almost $5 billion
after the exchange reopened following last week's record hack. US economic data
slate includes the October final S&P Global manufacturing PMI (9:45am), ISM
manufacturing and September construction spending (10am) and the Fed's Senior
Loan Officer survey (2pm); Fed speaker slate includes Chicago's Goolsbee
(11:15am). Treasury sells $95 billion of 13-week and $82 billion of 26-week
bills at 11:30am. Apple and Palantir report after the close.
Fundamental
Headlines
The
Economy
In
volume, the stats last week were very upbeat. However, the primary indicators’
score was one positive, one neutral and two negative while the inflation data
was one plus and three neutral. Overseas, the statistics were quite plentiful and
slightly tilted to the negative with one bad price measure.
While
these reports generally support both my forecasts for growth (muddle through) and
inflation (good as it is going to get but not any worse), both issues were up
for debate among the economic/investor set. For the moment, I am sticking with
my forecast; although I have the feeling that change is in the wind.
https://bonddad.blogspot.com/2026/10/a-mixed-bag-of-long-leading-indicators.html
On
the growth side, to date, the AI buildout has served as an economic accelerant.
However, the debate over the sustainability of AI buildout has become a hot
topic with a growing chorus of skeptics. The primary causes for the increased
uncertainty were disappointing earnings reports from some of the major players
as well as hiccups in financing the buildout.
The
AI balance sheet time bomb.
This
is not to say that the future of AI isn’t bright; but that it follows the
pattern of prior major technological innovations in the economy---massive over
investment followed by painful consolidation and then the emergence of the
ultimate beneficiaries. I give a lot of credence to that view which clearly
suggests some slowdown in economic growth if not an outright recession. I am
going to hold off on that call for the moment; but if history repeats itself,
one may very likely be in our future.
What
if…
On
the inflation side, at least short term, things are not much better. The Fed is
doing its usual ‘one the one hand, on the other hand’ routine---meaning that it
is doing nothing to quell inflationary forces. Given that the Fed’s virtually
spotless record of instituting the wrong policy at every critical economic
junction, I can’t really be positive about the potential outcome. My guess is,
again based on the Fed’s historical record, it will err on the side of policy
weakness, meaning higher inflation in the short term; followed by an
overtightening that leads to lower inflation but lower growth {recession?}
The Fed is fiddling while the economy runs hot.
Speaking
of inflation (and I wish that I weren’t), turmoil in Ukraine and the Middle
East has kept oil prices elevated. I have gone over the supply shortages/temporary
inflation argument ad nauseum. But the longer prices stay high and the longer
the warring parties continue to destroy production and refining infrastructure,
the further embedded in the economy higher prices become especially if there is
no sensible resolutions to the aforementioned conflicts whereby shortages
remain and transit/insurance fees stay high.
https://www.capitalspectator.com/the-rise-in-inflation-expectations-is-becoming-hard-to-ignore/
Further,
a totally irresponsible fiscal policy---the government reported a $2 trillion deficit
for FY2026--- is not likely to be cured anytime in the near future. God only
knows what the Iran war is costing the citizenry. And the dems who seem certain
to control congress have already laid out their plans for increased spending
and taxes. None of this is a plus regarding inflationary pressures. Add in
tariffs and it is clear that inflation is about more than oil prices
My
bottom line remains unchanged though my doubts on the trajectory of the
economy/inflation/AI buildout are increasing.
US
International
The October Japanese
manufacturing PMI was 53.3, in line; the Chinese manufacturing PMI was 52.0
versus 51.6; the German manufacturing PMI was 54.2, in line; the EU manufacturing
PMI was 52.7 versus 52.4; the UK manufacturing PMI was 52.8, in line.
Other
Update on the business cycle indicators.
Iran
Trump gives peace a chance.
Fiscal
Policy
The five tricks in policy debates.
https://www.thefreedomfrequency.org/p/beware-of-five-tricks-in-policy-debates
AI
The AI CDS market and how to trade it.
Investing
Timing
is everything.
Don’t ignore dividend growth stocks.
https://www.advisorperspectives.com/commentaries/2026/10/30/opposite-narrow-breadth-yield-everywhere
Why consumer stocks feel it first.
https://talkmarkets.com/article/real-wages-2026-why-consumer-stocks-feel-it-first
The Market owes you nothing.
https://www.safalniveshak.com/the-market-owes-you-nothing/
Tech isn’t the only problem.
The latest from BofA.
News (but not a Buy recommendation) on Stocks
in Our Portfolios
What
I am reading today
Visit Investing for Survival’s website (http://investingforsurvival.com/home) to learn more about our Investment Strategy, Prices Disciplines and
Subscriber Service.

No comments:
Post a Comment