
The Morning Call
11/13/26
This week kicks off my annual fund raising drive that helps keep me
working for you. Just go to the Donate button and enter the amount. Any monies
will be appreciated.
The
Market
Technical
Thursday
in the charts.
Thursday
in the technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
Friday morning setup:
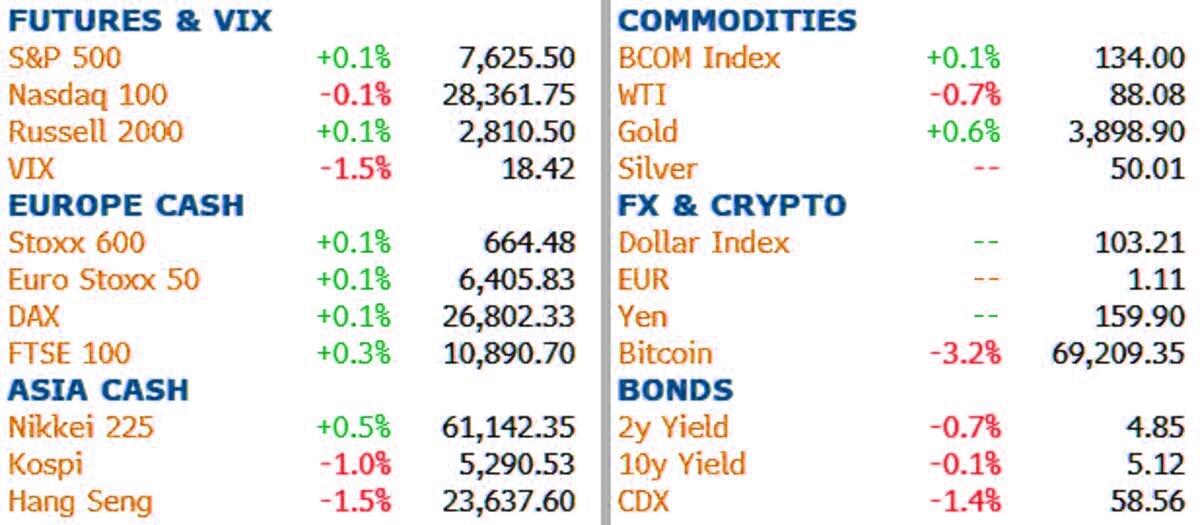
US futures are higher as traders move on from the Nvidia leadership shock and
shrug off a global Microsoft outage that is now in its second day, while the
IEA's call that the oil market is swinging to a surplus and a rebound in
short-dated Treasuries take some of the edge off the week's bond rout heading
into the PPI report. As of 8:00 am ET, S&P futures are 0.3% higher while
Nasdaq futures rise 0.1% and Dow futures add 0.2%. On Thursday, the S&P
fell 0.4%, the Nasdaq 100 slipped 0.3% and the Russell 2000 tumbled 1.7% after
Nvidia plunged as much as 14% at the open on Jensen Huang's ouster before
retail dip buyers dragged it back to a 4.3% loss, confirming our post
on the record opening retail bid. In premarket trading, Mag 7 stocks are
all higher except Microsoft (-2.7%), which is struggling to restore access to
Outlook, Teams and Copilot; Nvidia rises 3% and Alphabet 1.1%, while Cerebras
jumps 17% on blowout guidance and new deals with Oracle and Microsoft, and
Modine soars more than 20% on a report that Samsung is in talks to buy it. The
day's driver is inflation (again): October PPI at 8:30am is expected to
rise 0.4% m/m after September's 1.3% surge and comes after a hot CPI and a
Treasury selloff that left a December hike fully priced. Treasuries are mixed,
with the 2Y yield down 4bps to 4.84% as traders trim hike bets on the dip in
oil, while the 10Y is little changed around 5.12% after jumping 13.5bps on
Thursday; the combined Tuesday and Thursday jump in 10Y yields was the
biggest since April 2025. The Bloomberg dollar index steadies after
hitting an 18-month high, USD/JPY hovers just under 160 amid more Japanese
jawboning and the Aussie slides to its weakest since January. Brent trades near
$96 and WTI slips to $88.42 as the IEA's surplus call offsets Trump saying the
US doesn't need a deal with Iran; gold rebounds to around $3,900 but stays well
below $4,000, and Bitcoin is down 3% below $70,000. US economic data slate
includes October PPI (8:30am). Fed speaker slate includes Goolsbee (8:30am on CNBC),
Collins (9:10am and 10:35am), Logan (9:40am), Bowman (10:50am), Daly (12pm) and
Jefferson (7pm).
Fundamental
Headlines
The
Economy
US
October existing home sales fell 5.5% versus estimates of +0.3%.
https://talkmarkets.com/article/existing-home-sales-plunge-to-a-new-16-year
Note:
I have no problem with the above numbers and the author’s conclusion. But I would
dispute the notion that a 7% mortgage is somehow extreme. I bought my first house
in 1970 and the mortgage carried a 7% interest rate. That was normal and I didn’t
think anything about it. What is not normal is the absurdly low rates of the
past decade resulting from the QE’s. If a 7% mortgage is now considered
abnormal and it is a leading cause of low home sales, then new and existing
home sales will stay low until the generation that thinks 7% mortgages are too
high gets a lesson in economics.
The October federal budget deficit was $404 billion versus expectations
of $298 billion.
October PPI was up
0.3% versus consensus of +0.4%; core PPI was up 0.3%, in line.
International
The
September EU trade balance was -E10.3 billion versus projections of -E4.5
billion;
Q3 employment was flat versus an increase of 0.2%; the Q3 (2nd
estimate) GDP grew 0.4%, in line.
October German PPI
came in at +0.4%, in line.
Other
A review of current households debts.
More detail on yesterday’s jobless claims
number.
https://bonddad.blogspot.com/2026/11/its-still-historically-low-fire-economy.html
Iran
Iran considers withdrawing from nuclear nonproliferation
treaty.
Fiscal
Policy
The premium
on US Treasury debt is gone.
https://www.brookings.edu/articles/is-the-us-exorbitant-privilege-eroding/
Part two
https://klementoninvesting.substack.com/p/treasuries-lose-their-haven-status
Trump’s equity deals and the senate defense bill.
https://www.cato.org/blog/trumps-equity-deals-senate-defense-bill
Inflation
The inflation fight may be about to turn ugly.
2027
Goldman’s first try at the 2027 playbook.
AI
Ignoring AI’s potential.
https://trendlabs.com/an-unrestrained-demon/
But we can’t ignore Nvidia.
No one can fill Jensen’s leather jacket.
Shunning
immigrants could cost the US the lead in AI. (It is one thing to aggressively deport
criminals and felons. It is another to prevent qualified, highly skilled
workers from entering our labor force.)
Investing
Are
stocks priced for peak earnings?
https://www.carsongroup.com/insights/blog/earnings-check-in-priced-like-a-peak/
The
latest from Goldman.
Timeless
lessons.
Blue
Wave, Red Wave, Green Wave, And Timeless Lessons - Wealth Management - Carson
Group
The
bond market faces a reality check.
https://www.capitalspectator.com/the-bond-rally-faces-a-reality-check/
News on Stocks in Our Portfolios
What
I am reading today
How
weird is this?
Visit Investing
for Survival’s website (http://investingforsurvival.com/home)
to learn more about our Investment Strategy, Prices Disciplines and Subscriber
Service.

No comments:
Post a Comment