
The Morning Call
11/9/26
Today kicks off my annual fund raising drive that helps keep me working
for you. Just go to the Donate button and enter the amount. I know many
websites are free but most include a premium membership that requires a subscription
to access to the most informative articles. Subscriptions that I pay and provide
my readers the content for free. Any monies will be appreciated---even as
little as a dollar a week or a month will help.
The
Market
Technical
The S&P took a
beating last week as the blue wave and the uncertainty it created over the AI
buildout took its toll. It now hovers over its 200 DMA, having blasted through
its 50 and 100 DMAs plus the lower boundary of the August to November trading
range. Friday’s pin action halted Thursday plunge but only modestly. Certainly
not enough to assume that the worst is over. So the big technical question is,
is the sell off over? Given (1) Friday’s tepid rebound and (2) more importantly
the huge unknown hanging over the Market, i.e., what will be the ultimate
impact on the AI given that the dems now control the statehouses of some of the
major AI construction projects?, my guess is no. And, of course, none of this takes
into account the war in the Middle East. Clearly, I could be wrong, but the
Market is going to have to prove me wrong before I get off the sidelines.
A new test for tech
stocks.
https://www.capitalspectator.com/ai-meets-politics-a-new-test-for-tech-stocks/
The last man
standing has fallen.

The bond market was
up slightly on the week. And it certainly did not suggest a flight to safety,
though the lower rated credit spreads did widen some. TLT continues to trade
down across all timeframes and is below its 100 and 200 DMAs. So there’s
nothing to get jiggy about. That said, I continue to hold a small trading position
in a TIPS ETF.

GLD managed a
modest rally, reflecting increased economic and AI buildout fears. In the
process, it managed to close back above the lower boundary of its short term
trading range. However, it remains below all three DMAs. On the other hand, GDX
broke out of a downtrend dating back to early August and closed above its 100
DMA. So there is a flicker of promise. Still too soon to act.
Goldman cuts gold
target.

The dollar took Thursday’s equity drubbing in
stride but rallied big time of Friday, perhaps on the strong payroll number. It
remains on a pretty steep upward trajectory and above all three DMAs. And while
it has made a nice series of higher lows and higher highs and seems likely to
continue to do so, it remains in about the middle of a wide short term trading range.

Friday in the charts.
https://www.zerohedge.com/markets/blue-nami-hangover-chips-bounce-breadth-doesnt-hot-payrolls-put-december-hike-back-table?gift=eyJhbGciOiJIUzI1NiIsInR5cCI6IkpXVCJ9.eyJuaWQiOiIxMTMxMzI0Iiwic2VuZGVyVWlkIjoiUUhnc3BaZVVFS2E3RHhXM216eFlKbjhaWEFoMiIsImlhdCI6MTc5NDAwMTAzOCwiZXhwIjoxNzk2NTkzMDM4LCJhdWQiOiJ6aC1naWZ0In0.XJB3uuF4XunfKW4FuKOA2kJ_RA0-odeo-6zXN7YzllU
Friday in the technical stats.
https://www.barchart.com/stocks/momentum
https://www.barchart.com/stocks/market-performance
https://www.barchart.com/stocks/sectors/rankings
https://www.barchart.com/stocks/signals/new-recommendations
Friday’s week from hell.
https://www.zerohedge.com/the-market-ear/wall-streets-week-hell-panic-liquidations-and-next-big-trade?gift=eyJhbGciOiJIUzI1NiIsInR5cCI6IkpXVCJ9.eyJuaWQiOiIxMTMxMzE4Iiwic2VuZGVyVWlkIjoiUUhnc3BaZVVFS2E3RHhXM216eFlKbjhaWEFoMiIsImlhdCI6MTc5NDAwMDI2NiwiZXhwIjoxNzk2NTkyMjY2LCJhdWQiOiJ6aC1naWZ0In0.xEipOPU4Nl-17jNsMqwIh1wmMZT07INq5cavfcDPRh4
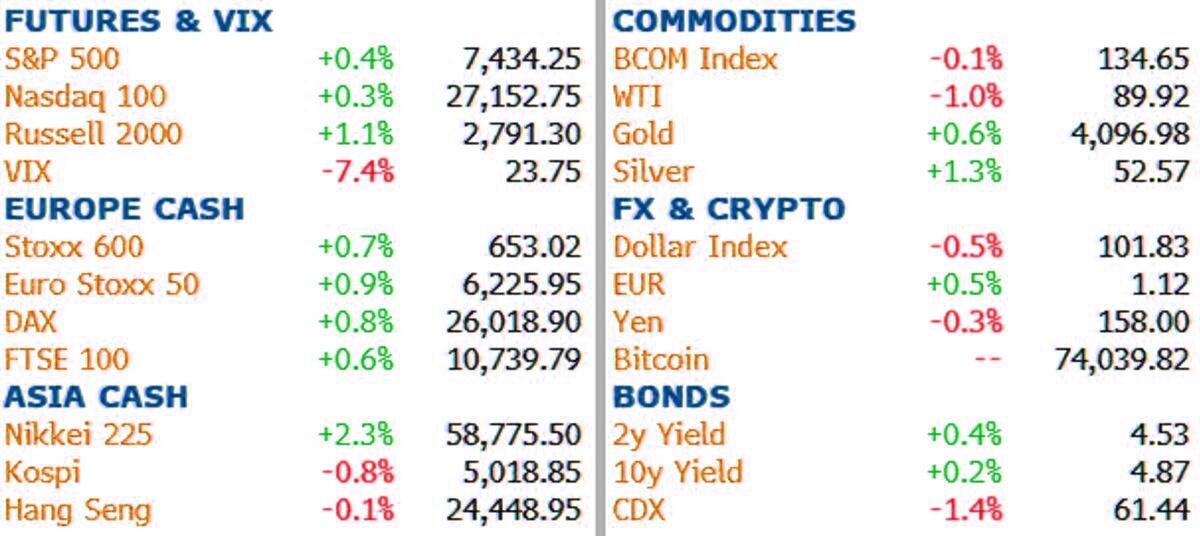
Monday morning
setup: US futures are higher as dip buyers return after the S&P's worst
week since April 2025, oil extends its biggest weekly drop since April 2020 on
Iran diplomacy hopes, and the market decides that Jensen Huang's affair
with a suspected Chinese spy is an Nvidia problem rather than an AI problem,
at least until the open; as a result, Treasuries are little changed with the
10Y at 4.86%. As of 8:15am ET, S&P futures are 0.9% higher while Nasdaq
futures gain 0.8% and Dow futures rise 1.1%, the latter a good read of where
the money is going. Cash stocks closed Friday with the S&P up 0.31% and the
Nasdaq 100 up 1.4%, but that barely dented a week in which the S&P lost
2.7% and the Philly semi index fell 12%. In premarket trading the Mag 7
ex-Nvidia is green, with Nvidia down between 4.4% and 4.9% after the
board launched an independent probe, while KKR, IFF and Barrick are higher
and Dole slides. The day's driver is oil (again): WTI is down 3.5% to
$87.66 and Brent is down 3.8% to $94.59 after Trump told CNN that further
strikes on Iran are highly unlikely if talks progress, with a further leg lower
on an unconfirmed report that Iran softened its Hormuz demands. Treasuries are
mixed and the curve is twist-flattening, with the 2Y around 4.53% as markets
price roughly a 79% chance of a December Fed hike; bunds are slightly weaker.
The Bloomberg dollar index is down 0.4%, with the kiwi leading G-10 after New
Zealand's incumbent National Party emerged from the election with a path back
to power. In commodities, gold is up 0.6% around $4,097, silver gains 1.3% near
$52.60 and copper is firmer; bitcoin holds around $74,000. US economic data
slate includes September final wholesale inventories (10am) and the NY Fed
one-year inflation expectations (11am). Fed speaker slate includes Bowman
(8:40am), Goolsbee (10am) and Barkin (12:15pm). The Treasury sells $58 billion
in 3-year notes at 1pm; US bond markets are shut Wednesday for Veterans Day.
Fundamental
Headlines
The
Economy
The
stats last week were upbeat as were the primary indicators (three plus, one
minus) with no inflation numbers. Overseas, the data was negative with one
neutral and one bad price measure.
While
these reports generally support both my forecasts for growth (muddle through) and
inflation (good as it is going to get but not any worse), both issues were under
intense debate following the election.
First,
the dem’s sweep was much larger than expected. That in itself shouldn’t have
been that great a surprise and even if it was, so what? The senate was not
veto-proof and Markets (count me in) love divided government. Generally,
because the succeeding two years is an agenda fight that usually ends in some
compromise that limits government growth. What’s not to like?
Another
positive is that Trump’s loss is a gain for Fed independence. That is not to
accuse the Fed of being political but removing the potential pressure from a
sitting president backed by a partisan congress at least gives the Fed some
psychological relief from White House harangues. Mind you, not that the Fed will
end up doing the right thing anyway, as history would suggest. But, at least,
it will be free of one potential negative influence.
To
be clear---in my opinion, (1) a democrat controlled congress is a plus. Not because
of their policy objectives but because we are likely to see a hamstrung fiscal
policy that at least won’t make current fiscal policy any worse and (2) not having
Trump pressuring the Fed doesn’t necessarily mean that it will make any better
decisions. As I frequently point out, at critical junctions, these ivory tower yahoos
haven’t ever gotten policy decisions right.
What
the election did change was the assessment of the future economics of the AI buildout.
The sweeping change in the state governors’ mansions of states that are centers
of the AI datacenter construction was a stunner. Given the less AI friendly democrat
attitude to the industry, economists and Wall Street are now reassessing whether
the current projected growth in the AI buildout can be sustained given the more
restrictive policy statements from those winning democratic governors.
If
barriers are raised that impede or, worse, halt construction, what happens to
the projected growth of the buildout and more importantly, the financing, both
on and off balance sheet that is already in place, to fund that projected
dynamic growth? Everyone is trying to figure that out right now---and, as yet,
we don’t have an answer. But most agree that whatever the outcome, it will be
less positive than previously thought.
Twilight in the markets.
https://giftarticle.ft.com/giftarticle/actions/redeem/ce7d2c7a-9b47-4dfa-910b-7370f04cee37
And
that carries both good news and bad news. The bad news is that the projected growth
rate of the AI buildout (and hence the economy) will be less than expected. How
much less. Too soon to determine. But clearly that will overhang the economic
projections as well as the Market until the answer become clearer.
The
good news is that less demand coupled with a less irresponsible fiscal policy (I
hope) would reduce inflationary pressures. Add in the democrats’ other
objectives to (1) reduce tariff s and (2) wind down the Middle East war and we could
see meaningful progress against inflation---assuming the Fed doesn’t f**k it up.
Again, how this all works out is currently unclear. So we can’t get too jiggy
until more on known.
The
bottom line here is that economic projections from any quarter have become a
lot more iffy. There is both good and bad potential news that will play on growth
and inflation. Until we have a better handle on the outcome of the various
aforementioned developments, a level of uncertainty will prevail which clearly
includes my own forecasts.
US
International
The September
Japanese leading economic indicators came in at 116.4 versus consensus of 116.7.
The September
German trade balance was E15.6 billion versus projections of E19.2 billion.
The October
Chinese CPI was 0.0%, in line.
Other
Record profit margins are about to get
squeezed.
https://talkmarkets.com/article/ppi-vs-cpi-are-record-profit-margins-about-to-get-squeezed
A deep dive into the employment numbers.
https://wolfstreet.com/2026/11/06/signs-pile-up-of-a-solid-and-tightening-labor-market/
Unhired or unfired?
Iran
Overnight news:
Trump says further
Iran strikes are "highly unlikely" if negotiations progress, while
Rubio calls Tehran's demands unacceptable.
US and Iran are
quietly negotiating a deal to avert a return to all-out war, though Washington
is tempering hopes:
Fiscal
Policy
The looming issues facing the new class of senators.
AI
Credit crunch imminent.
Microsoft
pulls the plug on Oracle.
Jensen Huang had a ‘relationship’ with an
alleged Chinese spy.
https://www.zerohedge.com/ai/jensen-huang-had-romantic-relationship-alleged-chinese-spy-reports
Follow up.
Investing
Another wave of bad news will be coming.
The latest from BofA.
Why this analyst is buying the AI dip.
Sticking to your playbook in the face wildly
gyrating headlines and Markets.
How
to spot a Market bubble.
Update on valuations.
Three risks that bolster the case for defensive stocks.
News (but not a Buy recommendation) on Stocks
in Our Portfolios
What
I am reading today
Consider this.
A
Couple of Rants - by Arnold Kling - In My Tribe
Visit Investing for Survival’s website (http://investingforsurvival.com/home) to learn more about our Investment Strategy, Prices Disciplines and
Subscriber Service.

No comments:
Post a Comment